Table of Contents
- What Is the Cheapest Roadside Assistance?
- Roadside Assistance Plan Comparison Table
- Roadside Assistance Without Insurance: Standalone Membership Plans
- Insurance Add-On vs. Standalone: Which Costs Less?
- Understanding Roadside Assistance Towing Limits
- Pay-Per-Use Roadside Assistance: When It Makes Sense
- What the Cheapest Plans Don’t Cover
- Local Roadside Help When You Need It Most
- Frequently Asked Questions
Last Updated: October 20, 2026
What Is the Cheapest Roadside Assistance?
The cheapest roadside assistance depends on how you buy it.
At Neptune Towing, we help drivers understand their options. When you’re stranded on I-44 with a dead battery, the cheapest plan doesn’t matter if it won’t cover your situation.
According to Forbes Advisor’s 2026 roadside assistance comparison, the lowest-priced plans often come with serious limitations. Some cap towing distance at 20 miles.
Roadside Assistance Plan Comparison Table
| Plan | Starting Price | Type | Towing Distance | Best For |
|---|---|---|---|---|
| Erie | $5/vehicle/year | Insurance add-on | 20 miles | Budget-conscious drivers with existing Erie policies |
| GEICO | $14/car/year | Insurance add-on | Not specified | Drivers seeking low-cost insurance add-on |
| American Family | $10-$20/year | Insurance add-on | Not specified | Drivers with existing American Family policies |
| Good Sam Platinum | $49.95/year | Standalone membership | Not specified | Drivers wanting standalone coverage |
| Better World Club | $66/year | Standalone membership | Not specified | Drivers prioritizing customer service |
| Neptune Towing | Call for pricing | Local on-demand service | Unlimited | Tulsa-area drivers needing immediate, damage-free help |
How We Evaluated These Plans
We looked at local alternatives like Neptune Towing, focusing on included services and real-world limitations.
A plan sounds great until it only covers 20 miles of towing and you’re stuck 35 miles from home, so we included towing distance limits, service call caps, and coverage details.
We also distinguished between insurance add-ons, which depend on keeping that policy active, and standalone memberships, which cover you regardless of your insurance situation.
Roadside Assistance Without Insurance: Standalone Membership Plans
Standalone roadside assistance memberships give you coverage that doesn’t depend on your auto insurance policy.
According to WalletHub’s 2026 roadside assistance guide, standalone plans typically cost between $50 and $100 per year. Better World Club, which MarketWatch ranks as its top roadside assistance plan for 2026, starts at $66 per year.
Standalone plans are an option if you don’t have auto insurance or prefer not to bundle services, and you choose the provider.
If you drive an older car or a vehicle you don’t insure heavily, a standalone membership might be a consideration. One emergency tow can be a significant expense, so an annual membership could offer value after one call.
Insurance Add-On vs. Standalone: Which Costs Less?
The sticker price is only half the story. The most suitable roadside assistance is the option with the lowest total cost for how you actually drive, so look past the advertised rate to what you’ll pay in year one and on renewal.
First-Year vs. Renewal: The Cost You Don’t See in the Ad
- Insurance add-ons are typically billed as a flat per-vehicle charge added to your existing policy. The rate usually renews at the same amount each term, but it’s tied to your policy: if you switch insurers, raise your deductible, or let coverage lapse, the roadside benefit goes with it.
- Standalone memberships often advertise a low introductory rate for the first year and then renew at a higher standard rate. Enrollment fees, per-call service fees, and add-on tiers can push the real first-year cost well above the headline number, so always ask for the renewal rate in writing before you enroll.
The lowest advertised membership price is often a first-year promotional rate, and the renewal rate is what matters for a multi-year comparison. Put the first-year total and the renewal total side by side, not just the monthly figure.
The Break-Even Math
Here’s the practical way to decide. Compare the annual cost of a plan against what you’d pay out of pocket for a single service call.
- If a plan’s cost is comparable to one tow or one jump start in your area, it could offer value after a single use. For drivers who break down even once every year or two, that math usually favors a plan.
- If a plan’s cost is significantly more than a single service call, you need multiple covered calls per year before it pays off, which most drivers never hit.
- Pay-per-use only wins if you genuinely go years without needing help. The moment you need one tow, the membership math flips.
The catch is that “covered” is doing a lot of work in that sentence. A plan that covers a 20-mile tow doesn’t break even on a 40-mile tow, you still pay the overage. Run the break-even against the service you’re most likely to need.
Which Is Cheaper for Your Situation?
There’s no universal winner. The cheapest suitable option depends on your profile:
- Occasional drivers with an active policy: An insurance add-on is usually the lowest total cost, since the add-on rides along at a per-vehicle rate.
- Commuters and families with multiple vehicles: Compare the per-vehicle add-on cost across every car against a single standalone membership that may cover the household. The math can flip once you insure three or four vehicles.
- Drivers between policies or with high deductibles: A standalone membership is the only option that doesn’t depend on an active policy, so it wins by default even at a higher sticker price.
The cheapest plan on paper is rarely the cheapest plan in practice. Compare first-year total against renewal total, run the break-even against the service you’re most likely to need, and match the plan to your vehicle count and driving pattern, not to the headline rate.
Understanding Roadside Assistance Towing Limits
Most roadside assistance plans include a towing distance limit, and that’s where many drivers get surprised.
Some plans include 20 miles of towing. That sounds reasonable until you’re stuck on a rural highway outside the Tulsa metro and need a specific repair facility.
Better World Club and Good Sam don’t specify towing distance limits in their advertised plans, which suggests more generous coverage, but read the fine print or call to confirm.
Local towing services like Neptune Towing don’t work on distance limits.
Before signing up for any roadside assistance plan, ask specifically about towing distance limits and what happens if you need to go beyond that distance. A plan that only covers 20 miles might leave you paying out of pocket for the remaining distance.
Pay-Per-Use Roadside Assistance: When It Makes Sense
Some drivers skip membership plans entirely and pay per service call when they need help.
The problem is cost and availability. A single tow can be a significant expense depending on distance and location, as can a jump start or a lockout service.
Pay-per-use also means waiting for availability. When you’re stranded, you’re calling whoever is available, not your chosen provider, no pre-established relationship or guaranteed response time.
This approach only makes financial sense if you genuinely never need roadside help.
What the Cheapest Plans Don’t Cover
The lowest-priced plans aren’t scams, they’re narrow. The savings come from limits that only surface when you actually need help, so read the plan for these specific gaps before you enroll.
Mileage Caps and Overage Charges
Most budget plans cap the tow distance they’ll pay for, commonly around 20 miles, sometimes less. Beyond the cap, you pay the overage per mile, often higher than a local tow would have cost. A 20-mile plan is fine if your usual shop is close; it’s a trap if you’re stranded on a rural stretch outside the metro and the nearest specialist is 35 miles away.
Per-Call and Service Fees
A plan can be “covered” and still cost you at the scene. Watch for:
- Service call fees charged each time you use the plan, separate from the membership fee.
- After-hours or holiday surcharges when you break down at night or on a weekend.
- Extra passenger or additional-stop fees if you’re not alone or need to stop somewhere en route.
Add those up and a plan with many fees can cost more on a single call than a pay-per-use local service.
Vehicle and Situation Restrictions
Budget plans often restrict what they’ll cover and when:
- Vehicle type exclusions, some plans exclude motorcycles, RVs, commercial vehicles, or heavily modified vehicles, and many are not set up for EV or Tesla towing, which requires flatbed equipment and specific handling.
- Accident and recovery exclusions, a plan that covers a mechanical breakdown may not cover a winch-out from a ditch, a vehicle recovery after a collision, or a car that’s off-road.
- Coverage tied to the policy, insurance add-ons typically only apply while that policy is active and the vehicle is listed on it.
- Geographic limits, some plans exclude service outside a defined area or outside the continental U.S.
The Fine Print That Decides the Call
Two clauses matter more than any other: the annual service-call limit (unlimited vs. a set number per year) and the definition of a “covered” breakdown.
When Neptune Towing responds to a call in the Tulsa area, we handle the situation in front of us: jump starts, lockouts, tire changes, fuel delivery, flatbed towing for damaged, luxury, Tesla, and EV vehicles, and vehicle recovery and winch-outs.
Before you sign up for any roadside assistance plan, ask specifically about the towing distance cap and overage rate, per-call and after-hours fees, vehicle-type exclusions, the annual call limit, and how the plan defines a covered breakdown. Those five answers tell you more than the advertised price ever will.
Plans with limited coverage work best for drivers who already have a policy with that carrier, stay close to home and their usual shop, drive a standard vehicle, and rarely break down. If any of those don’t describe you, or you drive an EV, a specialty vehicle, or travel outside the metro, a plan with broader coverage or a local on-demand service is often a better value.
Local Roadside Help When You Need It Most
When you’re stranded on I-44 near Tulsa or stuck in a parking lot in Bixby, the cheapest national plan doesn’t help much if there’s no local provider nearby.
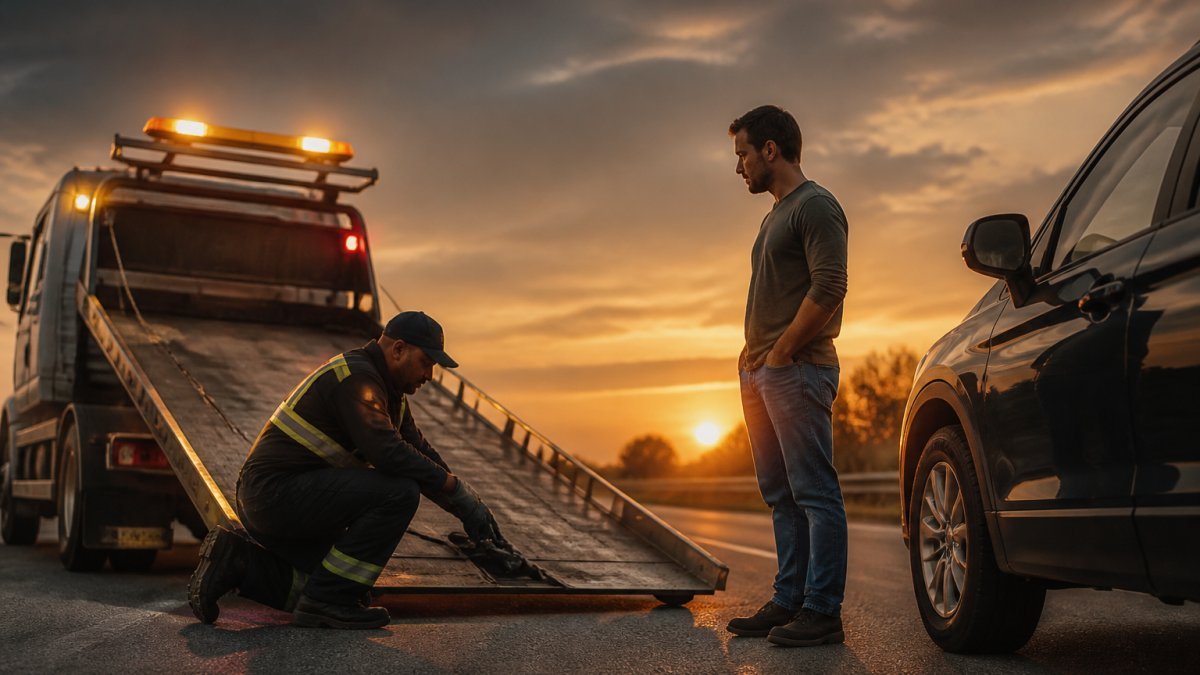
Neptune Towing serves Tulsa, Jenks, Bixby, Broken Arrow, Glenpool, Owasso, Sapulpa, and surrounding communities.
We specialize in damage-free flatbed towing, which matters if you drive a Tesla, luxury vehicle, or classic car.
For drivers in the Tulsa area, calling a local towing service can offer reliable service: the same person every time, someone who knows the roads and repair shops, and someone who actually cares about your vehicle.
Frequently Asked Questions
Can you get roadside assistance without insurance?
Yes. Standalone roadside assistance memberships let you purchase coverage directly without buying an auto insurance policy. Plans like Better World Club and Good Sam offer annual memberships that work independently of insurance. These options give you flexibility if you already have coverage elsewhere or prefer a separate service provider.
Is roadside assistance cheaper through insurance or a membership?
Compare total first-year costs, renewal prices, and what services each plan actually covers before deciding. The most suitable option isn’t always the best fit for your driving patterns.
How far will roadside assistance tow your vehicle?
Towing distance limits vary significantly between plans. Some plans cover 20 miles per service call, while others offer higher limits depending on the membership tier. This matters if you’re stranded far from home or a repair facility. Before choosing a plan, check whether the towing distance matches your typical driving routes. If you frequently drive long distances from your home area, a plan with a higher mileage cap may be worth the extra cost, even if the annual fee is higher.
What should I compare when choosing a roadside assistance plan?
Look at first-year price, renewal cost, towing distance limit, service call limits, and what services are included (jump-starts, lockouts, tire changes, fuel delivery). Also check response time and whether the plan covers motorcycles, RVs, or multiple vehicles. Consider your driving habits: if you rarely break down, pay-per-use might work. If you drive older vehicles or frequently travel long distances, an annual membership with higher limits makes more sense. Read the exclusions carefully, some plans don’t cover certain vehicle types or situations.
Is pay-per-use roadside assistance worth it?
Pay-per-use works only if you rarely need help. If you call for roadside assistance more than once or twice a year, an annual membership can often provide more predictable costs. Most drivers find value within the first service call or two. The real advantage of pay-per-use is flexibility if you’re a careful driver with a newer, reliable vehicle. For older vehicles, frequent long-distance drivers, or anyone who wants peace of mind without calculating costs later, an annual plan provides better value and immediate coverage without worrying about per-call charges.
When you need roadside assistance, the cheapest plan isn’t always the best plan. The best plan is the one that covers your actual situation, responds quickly when you need help, and doesn’t leave you stranded by distance limits or coverage exclusions. For drivers in the Tulsa area, Neptune Towing is ready to help 24/7. Call (539) 292-3074 when you need immediate roadside assistance, damage-free towing, or emergency help getting your vehicle to safety.