Last Updated: November 5, 2026
Quick Summary
Stay calm, write down the facts, and keep your answers short and factual when insurance adjusters call after a crash. You do not have to answer everything on the first call or give a recorded statement right away. Ask who is calling, what the recording is for, and get the adjuster’s name and claim number.
- Insurance adjusters work for the insurance company, not for you, even when the call sounds friendly.
- Gather the other driver’s information, your policy number, the police report number, and witness details before you call.
- Never admit fault, speculate about speed, or say you feel fine when injuries may still show up later.
- Ask for written questions and a short delay before agreeing to any recorded statement.
- Keep a communication log with dates, names, and what was said for every call.
Table of Contents
- Why Insurance Adjusters Call So Soon After a Crash
- Step 1: Get Your Facts Straight Before You Pick Up the Phone
- What to Say to an Insurance Adjuster After a Car Accident
- What Not to Say to an Insurance Adjuster
- Deciding Whether to Give a Recorded Statement to an Insurance Adjuster
- How Long an Insurance Adjuster Takes to Review a Claim
- Keeping a Written Record and Evaluating Any Settlement Offer
- Your Next Step: Getting Your Vehicle Safely Off the Road in Tulsa
- Frequently Asked Questions
Why Insurance Adjusters Call So Soon After a Crash
Insurance adjusters often reach out soon after a crash. That quick call is part of the insurer’s process, and it helps to know why before you pick up the phone.
Keep that in mind on your first call. The adjuster is not your advocate, and you do not have to answer every question on the spot. You are allowed to take your time, write things down, and call back when you are ready.
If you were driving the other vehicle or are not sure which insurer to deal with, you may hear from more than one company. If you are trying to work out how a towing company dispatch differs from an insurer-assigned tow, see Towing Company Vs Insurance Dispatch.
Step 1: Get Your Facts Straight Before You Pick Up the Phone
Before you talk to any adjuster, write down what you know while it is still fresh. Include the date, the time, the intersection or highway exit, and the weather and lighting. Sketch the positions of the vehicles if you can.
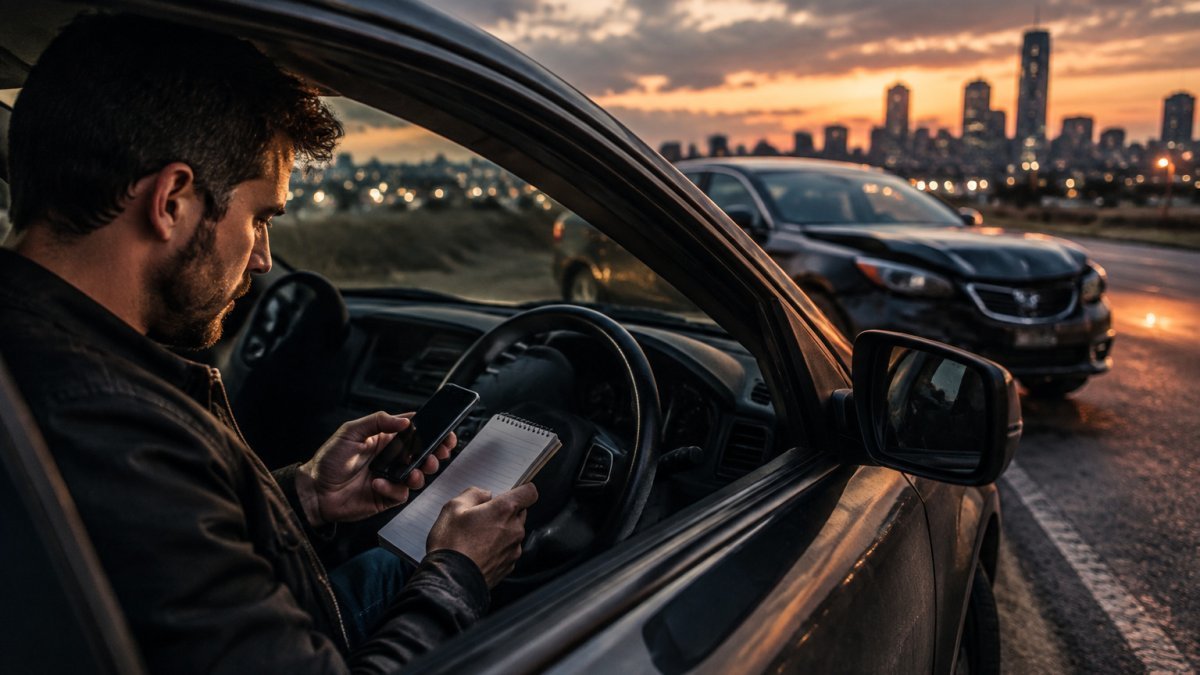
Next, gather the basics in one place:
- The other driver’s name, phone number, and insurance information
- Your policy number and claim number, if you already have one
- The police report number, if an officer responded
- Names and phone numbers of any witnesses
- Photos of the scene, the vehicles, and the license plates
Keep this list next to your phone. If you want a full post-accident checklist covering documentation and next steps, read What to Do After a Car Accident: Step-by-Step Guide. It helps you stay calm and avoids guessing later. If you are still on the roadside, focus on safety first. For immediate safety steps and how to get help now, see Car Breakdown: What to Do When You’re Stranded.
What to Say to an Insurance Adjuster After a Car Accident
When you do speak with an adjuster, stick to simple, factual statements. Tell them your name, the date and time of the crash, and where it happened. Describe what you saw in plain words.
Confirm the basic facts that are easy to verify, such as who was involved and whether anyone needed medical attention. Give your insurance information and let the adjuster know you will send any photos or documents they request.
Keep your answers short. If you do not know something, say so. “I’m not sure how fast the other car was going” is a fine answer.
Ask for the adjuster’s name, direct phone number, and claim number. Write these down. You will need them for every follow-up call.
What Not to Say to an Insurance Adjuster
Avoid admitting fault, even casually. Phrases like “I’m sorry, I didn’t see you” or “I think I was partly at fault” can be used against you.
Do not speculate about injuries. Many people say “I feel fine” right after a crash, then find neck or back pain a day later. Instead, say you are still assessing how you feel and will follow up with a doctor if needed.
Also avoid describing your own speed, distractions, or what you were doing on your phone unless the adjuster asks you directly. If the question is unclear, ask them to repeat it or to put it in writing.
Deciding Whether to Give a Recorded Statement to an Insurance Adjuster
A recorded statement is exactly what it sounds like: a phone call the adjuster records, transcribes, and drops into the claim file. It is not a formality.
Your own insurer vs. the other driver’s insurer. These are not the same conversation.
What to do before you agree. Ask three questions: Who is recording? What will the recording be used for? Will I receive a copy? Write down the answers.
Sample language you can use. Keep it short and polite:
- “I’m happy to help. I’d prefer to provide that in writing so the record is accurate. Can you send me the questions?”
- “I’m still being treated for injuries and my doctor has advised me to keep statements to the facts I can verify. I can confirm the date, location, and vehicles involved today.”
- “I’ll need to review my notes and the police report before I give a recorded statement. I can call you back on Thursday.”
- “I don’t have an estimate for speed. I can tell you what I saw, but I won’t guess at numbers.”
If you do give one. Stick to what you personally saw and did. Do not estimate speed, distance, or time if you are unsure. Do not characterize fault.
Watch out: a friendly adjuster who says “this is just routine” is still building a file that may be read back to you months later.
After the call. Ask for the transcript or recording.
How Long an Insurance Adjuster Takes to Review a Claim
Timelines vary a lot. A straightforward property damage claim with clear liability may move in a couple of weeks. A claim with injuries, disputed fault, or missing records can take much longer. Adjusters often need repair estimates, medical records, police reports, and photos before they can make a decision.
If you have not heard back within the timeframe the adjuster gave you, call and ask for a status update. Write down the date, the name of the person you spoke with, and what they told you. A simple log protects you if the claim stalls.
Keeping a Written Record and Evaluating Any Settlement Offer
Most claims are won or lost on paperwork, not on the phone call. Build one folder, paper or digital, and treat it as the claim’s spine.
A practical claim timeline. Every claim moves through the same rough stages, even if the pace varies:
- First contact (days 1-3). Confirm the claim number, the adjuster’s name and direct line, and the policy numbers involved. Note the date of first contact, it matters for deadlines later.
- Investigation (weeks 1-4). Gather the police report, photos, witness names, repair estimates, and towing receipts. Send copies, never originals. Ask the adjuster in writing what documents they still need.
- Medical treatment (ongoing). Keep every bill, explanation of benefits, and treatment note. Do not sign a broad medical-records authorization that releases your entire history; ask for a narrowly scoped release tied to the crash.
- Demand and negotiation. Once treatment is complete or a doctor says you have reached maximum improvement, you (or your attorney) send a demand package with records, bills, lost-income proof, and a written summary of the claim.
- Settlement or escalation. If the offer is fair and covers everything documented, you sign a release. If not, ask for the basis of the offer in writing and consider negotiation, mediation, or an attorney.
What to gather at each stage. At first contact: policy declarations, claim numbers, the other driver’s information.
How to evaluate a settlement offer. Do not compare the number to what feels fair, compare it to a written list of what you have actually lost. Build that list before you read the offer:
- Medical bills, past and future. Past bills are easy. Future care, physical therapy, follow-up visits, imaging, is where offers often fall short. Ask your doctor to put expected future treatment in writing.
- Lost income. Use pay stubs, a letter from your employer, or tax records. Do not estimate from memory.
- Property damage. Repair estimates, diminished value if the vehicle is newer, rental costs, and towing or storage charges you actually paid.
- Out-of-pocket costs. Prescriptions, rides to appointments, home help while you recover.
- Unresolved symptoms. If you are still hurting, the claim is not ready to close. A release signed before you know the full extent of an injury is very hard to undo.
Read the release before you sign. A release typically ends your right to pursue anything further from that insurer, including claims that have not surfaced yet.
Watch out: an early offer that arrives before your treatment is finished is usually priced on incomplete information, yours. Accepting it can close the door on bills that have not arrived yet.
Digital evidence and privacy. Photos, dashcam clips, and text messages are evidence, back them up and do not delete them. Protecting your privacy also means keeping conversations with insurance claim adjusters focused on the crash and sharing only information relevant to your claim.
Use this quick reference to keep the claim’s key steps and documents straight as you work through it.
| Stage | What to gather | Timing |
|---|---|---|
| First contact | Claim number, adjuster’s name and direct line, policy numbers | Days 1-3 |
| Investigation | Police report, photos, witness info, repair estimates, towing receipts | Weeks 1-4 |
| Medical treatment | Itemized bills, explanation of benefits, treatment notes | Ongoing |
| Demand and negotiation | Records, bills, lost-income proof, written claim summary | After treatment ends or maximum improvement |
| Settlement or escalation | Written basis for offer, itemized list of losses | Before signing any release |
Your Next Step: Getting Your Vehicle Safely Off the Road in Tulsa
If your vehicle is still on the roadway or unsafe to drive, your first priority is getting it moved. Learn what is involved in recovery towing before the truck arrives. Neptune Towing is an owner-operated, locally owned towing company serving Tulsa, Jenks, Bixby, Broken Arrow, Glenpool, Owasso, Sapulpa, and surrounding communities.
When you call, tell us where you are, what happened, and whether the vehicle can roll. We will get your car moved to a safe location, or to the repair shop you choose, so you can focus on the claim. Call Neptune Towing at (539) 292 3074 for 24/7 roadside assistance.
Frequently Asked Questions
Should you give a recorded statement to an insurance adjuster?
You are generally not required to give a recorded statement to the other driver’s insurer, and you should be cautious about doing so before you understand your situation. Your own insurer may ask for one under your policy terms. If you agree, keep it factual: state what you saw, what you did, and when. Avoid guessing about speed, distance, or fault. You can ask to review the questions in advance, and you can request a written copy of the statement. If injuries, liability, or a large claim are involved, a short consultation with an attorney before speaking on the record is a reasonable step.
What should you not say to a claims adjuster?
Avoid admitting fault, apologizing in a way that sounds like an admission, or guessing about speed, distance, or what the other driver did. Do not describe injuries as minor until you have been evaluated, because symptoms can appear days later. Avoid signing anything, including a medical authorization or release, until you understand what it covers. Stick to the facts you directly observed. If you are unsure of an answer, say so and offer to follow up once you have checked.
How long does it take an insurance adjuster to review a claim?
Timelines vary with the complexity of the accident, whether there are injuries, and how quickly records and repair estimates arrive. Simple property damage claims can move in a few weeks, while claims involving injuries, disputed liability, or a total loss often take longer. Ask the adjuster for a claim number and a clear list of what they still need from you. Keep a log of every call, including the date, time, name, and what was discussed, so delays are easy to document if the claim stalls.
How do you respond if an insurance adjuster’s offer seems too low?
Do not accept the first offer on the spot. Ask the adjuster to explain how they calculated the number, and request the estimate in writing. Gather repair invoices, medical bills, and photos that support a higher figure. You can respond with a written counteroffer that references specific documentation. If the claim involves injuries or the dispute continues, consider speaking with an attorney before signing a release, because a signed release usually closes the claim permanently.